The Parish Development Model was designed to move government planning and economic support closer to households. Its revolving funds are expected to finance income-generating activities and continue supporting new beneficiaries as earlier borrowers repay. Reports of low recovery in some districts therefore raise questions that go beyond individual defaulters. They test whether beneficiary selection, project appraisal, financial education, monitoring and enforcement were strong enough from the beginning.
Parliamentary scrutiny of programme implementation has highlighted concerns over repayment and accountability. Low recovery does not automatically prove theft. Crop failure, livestock disease, delayed disbursement, poor market access and misunderstanding of programme conditions can all affect repayment. An investigation must distinguish households that faced genuine business losses from cases involving ghost beneficiaries, political interference, weak records or deliberate refusal to repay.
The first evidence trail is the beneficiary register. Each parish should have a verifiable list showing the applicant, national identification details, enterprise selected, amount received, disbursement date and repayment schedule. Investigators should compare digital records with bank or mobile-money transactions and conduct sample visits. A name on a database is not sufficient proof that the intended person received and controlled the money. Duplicate identities, inactive accounts and payments routed through intermediaries are major warning signs.
Selection procedures also require examination. Parish committees should apply published criteria and record their decisions. Where beneficiaries were selected because of political connections, family relationships or pressure from local leaders, programme quality is likely to suffer. Minutes, attendance lists and conflict-of-interest declarations can show whether decisions were properly made. Complaints from unsuccessful applicants should be logged and resolved through an independent channel rather than by the same officials being challenged.
Enterprise appraisal is equally important. A borrower may be willing to repay but unable to succeed if encouraged into an overcrowded activity without access to inputs, veterinary care, storage or buyers. Extension officers should confirm that proposed enterprises are suitable for local conditions. Investigators should examine whether the same standard business plans were copied for many beneficiaries and whether training occurred before disbursement. Attendance sheets alone do not prove that useful training was delivered.
The movement of money must be followed from the Treasury to the final beneficiary. Delays at any stage can destroy seasonal farming plans. A person receiving agricultural funds after the planting window may divert the money or undertake a weaker project. Transaction timestamps can reveal whether delays occurred in central release, district processing, parish administration or financial-service providers. Fees and unexplained deductions should also be checked against programme rules.
Recovery procedures must be fair and consistent. Beneficiaries need clear statements showing what is due, when it is due and how to pay. Local officials should not collect cash without official receipts and immediate recording. Digital repayment channels can reduce leakage, but users need support when systems fail. Authorities should separate administrative mistakes from genuine default and fraud. Aggressive enforcement against poor households while politically connected borrowers remain untouched would undermine public confidence.
Programme managers should publish parish-level performance information, including disbursements, active enterprises, repayments, arrears and verified jobs or income gains. Privacy must be protected, but aggregated data can show which areas need support and which patterns require investigation. High repayment alone should not be the only measure of success; beneficiaries may repay by selling assets or borrowing elsewhere. The programme’s purpose is sustainable household income, not merely movement of money through accounts.
Corrective action should combine recovery with programme repair. Officials responsible for ghost beneficiaries, forged documents or diversion should face investigation under the law. At the same time, viable enterprises affected by drought, disease or market shocks may need restructuring, technical assistance or realistic repayment adjustments. Independent verification is necessary to prevent hardship claims from becoming another avenue for favouritism.
The Parish Development Model carries high public expectations and large financial commitments. Protecting it requires more than public warnings to beneficiaries. Government must examine the full chain of responsibility: policy design, local selection, financial systems, extension support, market access, monitoring and recovery. Transparent records and timely investigations can show whether low repayment reflects economic hardship, weak administration or deliberate abuse—and ensure that revolving funds continue reaching the households they were created to serve.
Sources: Parliament of Uganda, https://www.parliament.go.ug/; Ministry of Local Government, https://molg.go.ug/; Parish Development Model Secretariat, Government of Uganda.
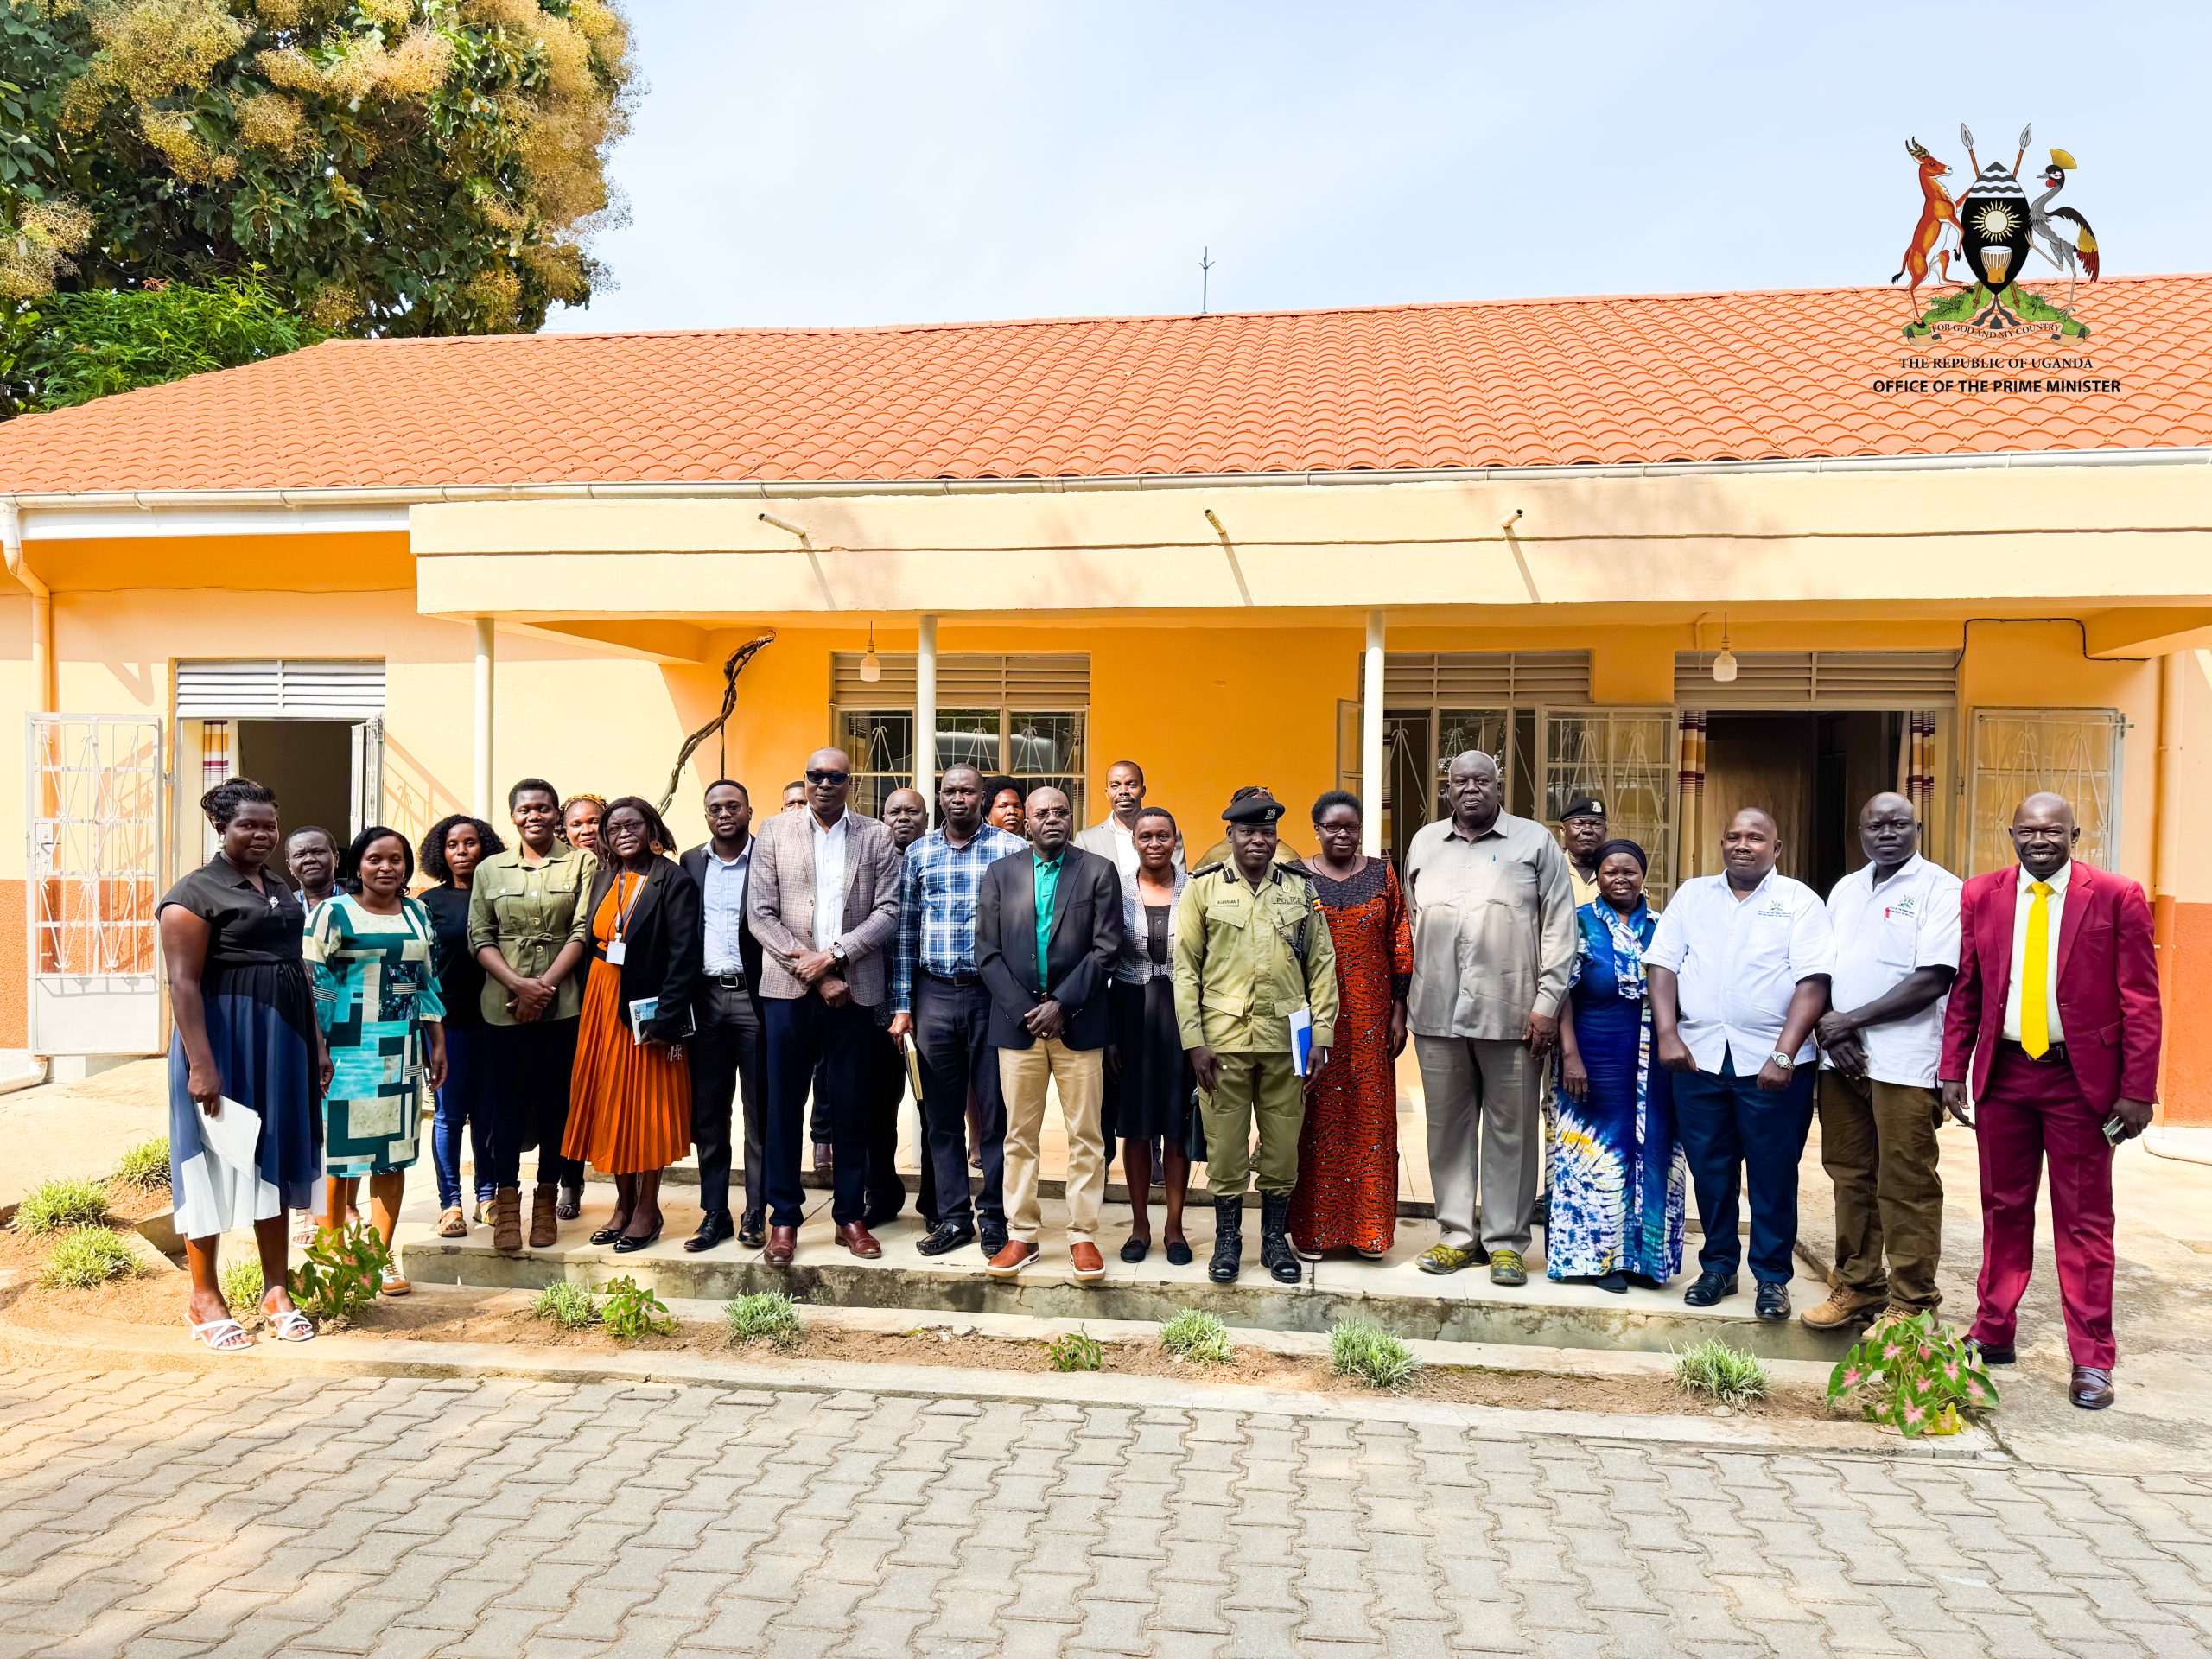
Photo credit: Office of the Prime Minister, Uganda.